
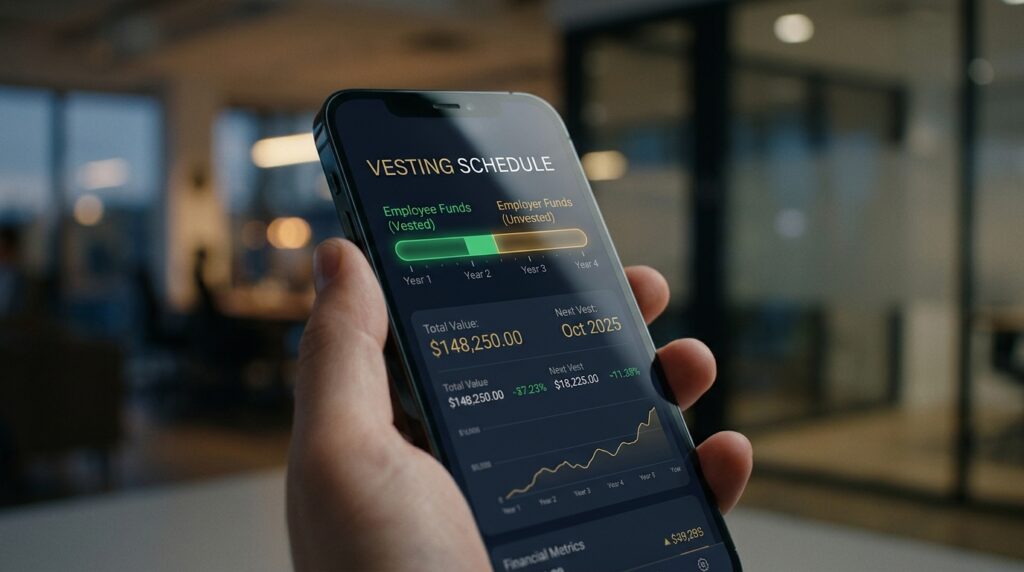
You contributed generously to your 401(k) this year, expecting full ownership of every dollar. But when you switched jobs, a portion of your employer contributions vanished. This common confusion stems from not understanding what a 401k vesting schedule is. Many employees assume their retirement savings are theirs to keep immediately, unaware that employer contributions are often tied to job tenure. If you leave too soon, those funds may become forfeited funds, effectively reducing your total retirement portfolio.
Quick Takeaway: A 401(k) vesting schedule determines when you gain full ownership of employer-matched contributions, typically requiring you to work for a specific period to avoid losing these funds.
In the following sections, we will demystify how cliff vesting and graded vesting work, clarify how retirement plan benefits accrue over time, and provide strategic advice to protect your hard-earned money. By the end, you will know exactly how to check your summary plan description and ensure you maximize your long-term wealth.
Understanding the Basics of 401k Vesting
When you contribute to a 401(k), you might assume that every dollar in the account belongs to you immediately. However, the money your employer puts in follows different rules. Vesting is the process by which you earn the right to keep employer-provided funds. Until you are fully vested, you do not legally own those assets.
This concept is central to understanding your total retirement plan benefits. If you leave a job before the vesting period ends, you may lose access to certain portions of your balance. Knowing how this mechanism works helps you make informed decisions about your career and financial security.
Employee vs. Employer Contributions
It is crucial to distinguish between the two primary sources of funds in a 401(k) account. Your own contributions are treated differently from those made by your company.
| Contribution Type | Vesting Status | Ownership Rule |
|---|---|---|
| Employee (Pre-tax/After-tax) | 100% Vested | You own it immediately |
| Employer (Match/Profit Sharing) | Variable | Depends on schedule |
Your personal contributions are always 100% vested. This means that if you quit today, you can roll over your own money into a new plan or an IRA without losing a penny. You have complete control over these funds from day one.
In contrast, employer contributions are subject to a vesting schedule. These include matching contributions, profit-sharing allocations, or other discretionary deposits. You do not own these funds until you meet specific criteria, usually related to your job tenure.
Why do employers implement these restrictions? It is primarily a risk management strategy. Companies want to incentivize long-term loyalty and reduce the financial impact of high turnover. Without vesting, an employee could join a company, receive a full match, and leave after six months, taking the employer’s money with them.
Pro Tip: Always check your summary plan description to see the exact vesting schedule. Some plans use rapid vesting, while others span five years. Knowing the timeline helps you calculate your true net worth.
If you leave before you are fully vested, the unvested portion becomes forfeited funds. These amounts typically revert to the plan to be redistributed among other participants or used to offset plan expenses. Therefore, understanding these ownership rules is essential for any long-term financial planning.
Common Types of 401k Vesting Schedules
When evaluating what is 401k vesting schedule policies, you will typically encounter two primary structures. These models determine how quickly employer contributions become your permanent property. Most companies choose one of these two methods to balance employee retention with company financial liability.
Understanding these distinctions is crucial for planning your career moves. The specific schedule dictates when you can walk away with the full value of your retirement account.
Cliff Vesting Schedule
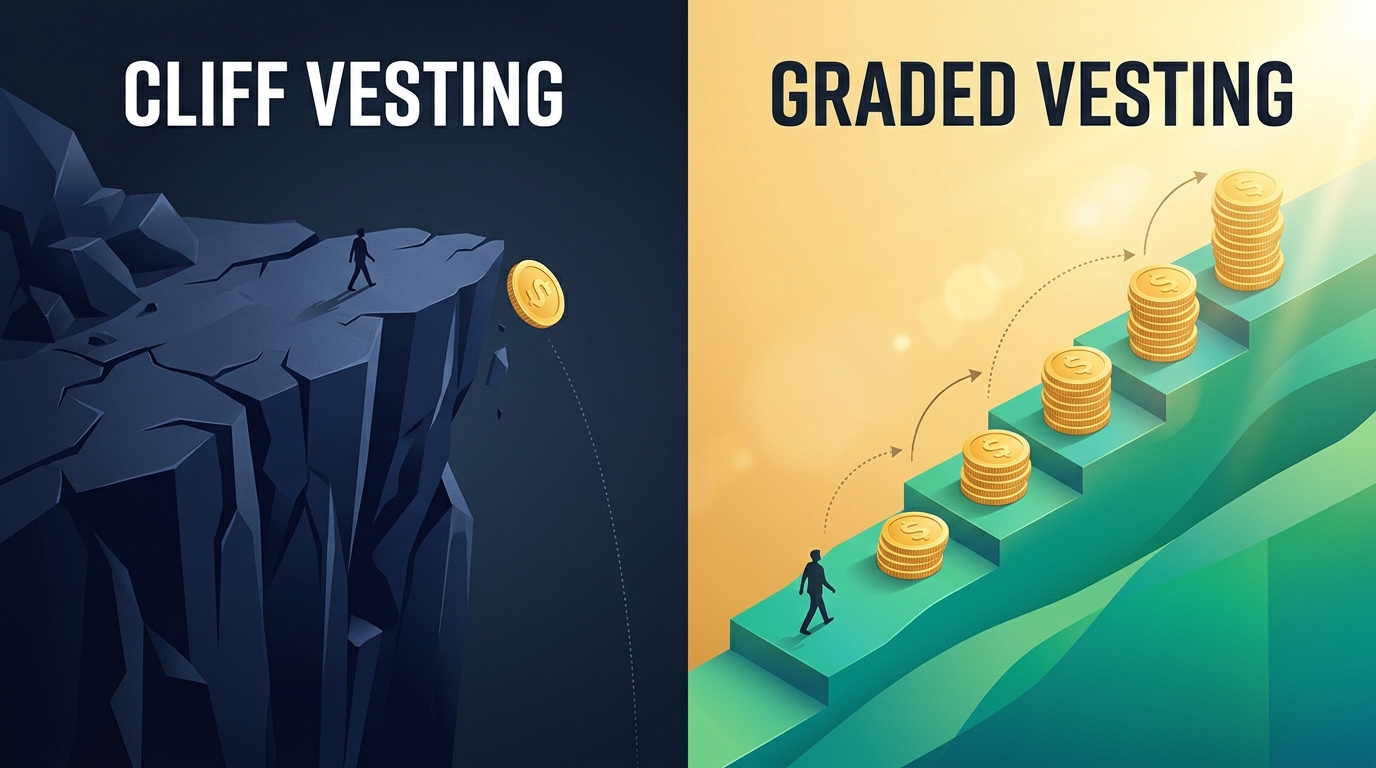
Cliff vesting is the simplest and most common structure in the corporate world. Under this model, you own 0% of employer contributions for a set period. Then, at a specific milestone, you become 100% vested.
For example, a plan might state that you are fully vested after five years of job tenure. If you leave after four years and eleven months, you forfeit all employer money. However, if you stay for the full five years, you keep every penny contributed by your employer.
This structure creates a strong “golden handcuff” effect. It encourages employees to stay with the company until the cliff date arrives.
Graded Vesting Schedule
Graded vesting offers a more gradual path to full ownership. Instead of a single jump, your ownership percentage increases incrementally each year. This provides a safety net if you leave before the final year.
A typical graded schedule might look like this:
-
- Year 1: 20% vested
- Year 2: 40% vested
- Year 3: 60% vested
- Year 4: 80% vested
- Year 5: 100% vested
This approach feels less punitive to employees who might leave mid-career. You still retain a portion of the employer contributions even if you do not complete the full term. It also allows for partial liquidity if you need to cash out part of your account during a job transition.
Pro Tip: Always check your summary plan description to see if your plan includes immediate vesting. While rare, some small employers or profit-sharing plans make contributions 100% vested immediately, giving you total control from day one.
To help you compare these options effectively, review the table below.
| Category / Scenario | Timeline / Key Factor | Action Required |
|---|---|---|
| Cliff Vesting | 0% to 100% at Year 5 | Stay until the exact 5-year mark to avoid forfeiting all forfeited funds. |
| Graded Vesting | 20% increase per year | Calculate your current vested percentage before resigning. |
| Immediate Vesting | 100% from Day 1 | Verify this in your plan documents, as it is an exceptional benefit. |
Knowing which model applies to your specific plan allows you to make informed decisions about your retirement plan benefits. It ensures you are not surprised by the amount of money you can actually take with you when you change jobs.
How Employer Match Vesting Works in Practice
Understanding how employer contributions interact with your tenure is crucial for protecting your retirement savings. Most plans use job tenure as the primary trigger for unlocking ownership rights. This means the longer you stay with your employer, the greater your stake in the matched funds.
Vesting typically begins on your hire date or the start of a plan year. Depending on your specific 401k vesting schedule, you might need to work for one, three, or six years to gain full ownership. For instance, a common structure requires two years of service before any employer money becomes yours.
Calculating Your Vested Balance
To determine exactly what you own, you must calculate your vested balance. This figure differs from your total account balance because it excludes unvested employer contributions.
You can find these details in your summary plan description or quarterly statements. Here is how to break down the calculation:
-
- Identify your total employer contributions in the account.
- Determine your current job tenure in years.
- Apply the specific percentage from your plan’s vesting schedule.
- Add this vested amount to your fully vested employee contributions.
Consider a scenario where you have $10,000 in employer matches. If your plan uses graded vesting and you have worked for two years, you might be 40% vested. This means you own $4,000 of that match. The remaining $6,000 stays with the plan if you leave.
| Tenure | Vested Percentage | Vested Amount ($10k Match) |
|---|---|---|
| 1 Year | 20% | $2,000 |
| 2 Years | 40% | $4,000 |
| 3 Years | 60% | $6,000 |
| 5 Years | 100% | $10,000 |
Leaving a job before reaching 100% vesting results in forfeited funds. These dollars are permanently removed from your account and returned to the plan or used to offset administrative costs. You cannot roll over unvested money to a new employer or an IRA.
Job changes significantly impact your 401k ownership rules. If you switch companies, you start a new vesting clock for the new employer’s retirement plan benefits. Your old unvested funds are lost, while your vested portion can be rolled over to preserve tax-deferred status.
Pro Tip: Always review your summary plan description before accepting a new job offer. Knowing if the new employer uses cliff vesting or graded vesting helps you calculate exactly how much money you risk losing if you leave early.
Strategic Considerations for Employees
Understanding how a 401k vesting schedule impacts your wallet is crucial for long-term financial health. Many employees assume all retirement savings belong to them immediately, but this is not always true. Your ownership of company-matched funds often depends on your job tenure.
To avoid surprises, start by reviewing your plan documents. The Summary Plan Description (SPD) is a legal document that outlines the specific rules of your retirement plan. It details exactly how and when you earn full ownership of employer contributions.
What Happens If You Leave Early?
Leaving a job before you are fully vested can result in financial loss. If you quit or are terminated before meeting the vesting requirements, you may forfeit unvested employer matches. These forfeited funds typically return to the company’s pool or offset future plan expenses.
You will usually keep 100% of your own pre-tax or after-tax contributions. However, the matching dollars granted by your employer remain at risk until the schedule is complete. This distinction is vital when calculating your total potential retirement assets.
Consider this scenario:
-
- You have contributed $10,000 personally over two years.
- Your employer matched $3,000 of that amount.
- Your plan uses a cliff vesting schedule requiring five years.
- If you leave after three years, you keep the $10,000 but lose the $3,000 match.
Pro Tip: Always request a copy of your Summary Plan Description before accepting a new job offer. Do not rely solely on verbal assurances from HR about vesting terms.
When evaluating new job opportunities, compare the retirement benefits carefully. A higher salary might be offset by a strict graded vesting schedule that delays full ownership. Look for plans with immediate vesting or shorter timelines to minimize risk.
Strategic planning involves balancing career moves with your retirement goals. If you are close to full vesting, staying an extra year might be financially beneficial. Conversely, if a new offer provides significantly better compensation, the cost of forfeited funds may be negligible.
Use this simple checklist before making a decision:
-
- Confirm your current vesting status.
- Calculate the exact dollar amount at risk.
- Compare the new employer’s retirement plan benefits.
- Assess whether the salary increase outweighs the potential loss.
By proactively managing these details, you protect your hard-earned savings. This approach ensures that your career transitions do not undermine your long-term financial stability.
Key Takeaways on 401k Ownership Rules
Understanding what is 401k vesting schedule is essential for maximizing your retirement security. The most critical rule to remember is that vesting applies only to employer contributions. Your own salary deferrals and the investment returns on that money belong to you from day one, regardless of your tenure.
Cliff vs. Graded Vesting
Most plans utilize one of two primary structures. Cliff vesting requires you to complete a specific period of service, often three or five years, before gaining full ownership. If you leave before that milestone, you forfeit all employer-matched funds. In contrast, graded vesting allows you to earn a percentage of the match annually. This structure provides partial ownership even if you leave early, reducing the risk of losing significant benefits.
- Cliff Vesting: All-or-nothing ownership after a set period.
- Graded Vesting: Incremental ownership increases each year.
- 100% Vesting: Full ownership of all employer money.
Take Action Today
Do not assume you understand your rights without reviewing the official documentation. Your summary plan description contains the specific job tenure requirements and retirement plan benefits unique to your employer. Misunderstanding these terms can lead to unnecessary forfeited funds if you change jobs prematurely.
Pro Tip: Log into your 401(k) provider’s website or request your latest statement to verify your current vesting percentage. This simple check ensures you are making informed decisions about your financial future.
Review your plan documents today to confirm your exact schedule. Knowing whether you are under cliff vesting or graded vesting empowers you to negotiate better terms or plan your career moves with greater confidence.
Frequently Asked Questions
Q: Do I lose my own 401k contributions if I leave before vesting?
No, you never forfeit money you contributed directly from your paycheck. Vesting rules apply only to employer contributions and any investment gains associated with those specific funds. You retain full ownership of your personal savings regardless of your job tenure or when you depart.
Q: What is the most common 401k vesting schedule?
The most prevalent structure is cliff vesting, which grants 100% ownership after three years of service. Many employers also use graded vesting, where ownership increases incrementally over five years. To confirm your specific timeline, review your summary plan description provided by your HR department.
Q: Can I roll over unvested 401k funds to a new job?
No, you cannot transfer or roll over forfeited funds that you have not yet earned. Upon separation, any unvested employer contributions are typically returned to the plan or forfeited according to the plan’s terms. You can only move the vested portion of your account balance to a new employer’s plan or an IRA.
Q: Does vesting affect my 401k loan eligibility?
Vesting status does not determine your ability to take out a loan, but the loan balance is secured against your vested account value. If you leave your job with an outstanding loan, the unvested portion of the account cannot be used to repay the debt. This may result in the loan being treated as a taxable distribution if not repaid promptly.
Q: Is a 401k vesting schedule the same as a profit-sharing plan?
No, these are distinct concepts where the vesting schedule is a rule within various retirement vehicles. A profit-sharing plan is a specific type of retirement plan benefits structure where contributions depend on company profits. Vesting schedules, such as cliff vesting or graded vesting, can apply to both 401(k) matches and profit-sharing allocations alike.
Conclusion
Understanding how your employer’s contributions are released is a critical component of building long-term financial security. A robust retirement strategy relies not just on how much you save, but on when you actually own those funds. To navigate this effectively, you must grasp the fundamental difference between employee and employer contributions, as only the latter are subject to vesting rules. It is equally vital to recognize the distinct types of schedules, such as cliff vesting, which grants full ownership after a specific period, versus graded vesting, which releases funds incrementally over time. Additionally, knowing your specific timeline allows you to plan for career changes or job transitions without risking the forfeiture of hard-earned employer matches.
By thoroughly reviewing your plan documents, you ensure that you are not leaving potential wealth on the table due to a lack of awareness. This knowledge empowers you to make informed decisions about your tenure and investment choices, aligning your employment history with your broader financial goals. Ultimately, clarity on what is a 401k vesting schedule transforms a complex HR policy into a strategic asset for your future.
We encourage you to share your own experiences with different vesting schedules in the comments below. Whether you have faced a cliff vesting challenge or benefited from immediate graded vesting, your insights can help others navigate this often-confusing aspect of retirement planning.
Disclaimer: This guide is intended for informational and educational purposes only and does not constitute formal legal, financial, or tax advice. Always consult with your institution or a qualified professional for individual guidance.